GIFT City: How Smart NRI Money Is Quietly Moving Home
Something quietly happened in India between 2020 and 2025 that fundamentally rewrote how serious NRI wealth should be structured. If you are an NRI, OCI, or foreign national with money in India, this is the most important article you will read this year.
GIFT City for NRIs has quietly become the smartest way to bring money home. Through India’s first International Financial Services Centre (IFSC) in Gujarat, non-resident investors can now hold Indian funds in US dollars, skip rupee conversion, and — most importantly — pay zero TDS on mutual fund exits. Here’s how the new structure works, and why smart money is already moving.
The Cousin in Dubai. The Brother in London. The Friend in Toronto.
Every Indian family has them.
The brother who moved to London ten years ago and now sends a part of his bonus home every year to “invest in India.” The cousin in Dubai who has been buying Indian mutual funds since 2018. The school friend in Toronto who quietly built a ₹4 crore Indian portfolio while you were not watching.
They all have something in common. They are using the same structure they set up when they first moved abroad. NRO account opened in 2014. SIPs registered in 2016. A relative’s bank account quietly used as a routing layer. A CA in India who files their returns every July and tells them “everything is fine, sir.”
And nearly all of them, even the wealthy ones, especially the wealthy ones, are quietly losing 2 to 3% of their portfolio’s value every single year to tax friction, TDS lock-ups, and currency conversion drag.
Over 10 years, on a ₹5 crore portfolio, that is roughly ₹1 crore quietly leaving the table. Without a single bad investment decision.
This is not because they were careless. It is because the rules changed, and nobody told them.
What Is Actually Happening, In Numbers
Before we go deeper, here is the scale of what India built while most NRI families were still routing money through structures designed before 2020.
766+
IFSC entities registered
$22B+
Capital committed
USD 500
New retail minimum
0%
TDS on MF exits
2030
Tax holiday extended to
JP Morgan, Barclays, Aditya Birla, DSP, ICICI Prudential, Mirae Asset, and 760+ others have moved in. That is not retail enthusiasm. That is sovereign and institutional capital making a structural bet on what comes next. Now let us look at why.
What Most NRIs Are Still Doing (And Why It Is No Longer Smart)
Let’s start with the painful truth. If you are an NRI today, your money in India is probably moving through one of these pipes.
An NRO account that earns 6% interest, and gets 30% TDS deducted on every rupee of that interest.
An NRE account that is tax free, but routes through Rupee conversion every time money comes in or out.
Indian mutual funds that deduct 12.5% to 20% TDS on every redemption, forcing you to file tax returns in India just to claim refunds.
A relative’s resident account that you “trust” to hold and manage money, which is technically a FEMA violation.
PIS accounts with the operational complexity of running a small business.
Every single one of these structures was the correct answer five years ago. Every single one is now actively burning your wealth, slowly, silently, and entirely legally, because India built something better and most CAs simply have not updated their playbook. That “something better” is GIFT City.
Side By Side: The Old Way vs The New Way
Here is what actually happens to an NRI’s rupee in each system. Not in theory, in steps.
Old Way, Mainland
NRO + SEBI Mutual Fund
Step 1. USD converted to INR at bank’s spread. 1 to 2% conversion loss.
Step 2. Money sits in NRO. 30% TDS on every rupee of interest earned.
Step 3. SIP into Indian fund. Annual CA fees, ITR filing every July.
Step 4. Redemption day. 12.5 to 20% TDS deducted at source.
Step 5. File ITR next year, wait 6 to 8 months for refund.
Step 6. Repatriate. Another conversion. Another 1 to 2% lost.
Net friction: 2 to 3% per year on entire corpus
New Way, IFSC
GIFT City IFSC Fund
Step 1. USD stays as USD. Zero currency conversion.
Step 2. Money sits in IFSC account. Interest on FCY deposits fully exempt.
Step 3. Invest in IFSC fund. One regulator (IFSCA), one jurisdiction.
Step 4. Redemption day. Zero TDS. Full amount in your account.
Step 5. No India ITR required for this flow.
Step 6. Repatriate in USD. No second conversion. No RBI approval cycle.
Net friction: roughly zero
Look at Step 4 alone. The difference is the gap between getting your full ₹50 lakh redemption today, and waiting 8 months to recover the ₹6 to ₹10 lakh that was deducted at source. Multiplied across every redemption, every dividend, every interest payment, over every year of your investing life.
What Is GIFT City, Really?
GIFT stands for Gujarat International Finance Tec City. The name buries the point. Here is what it actually is, in plain English.
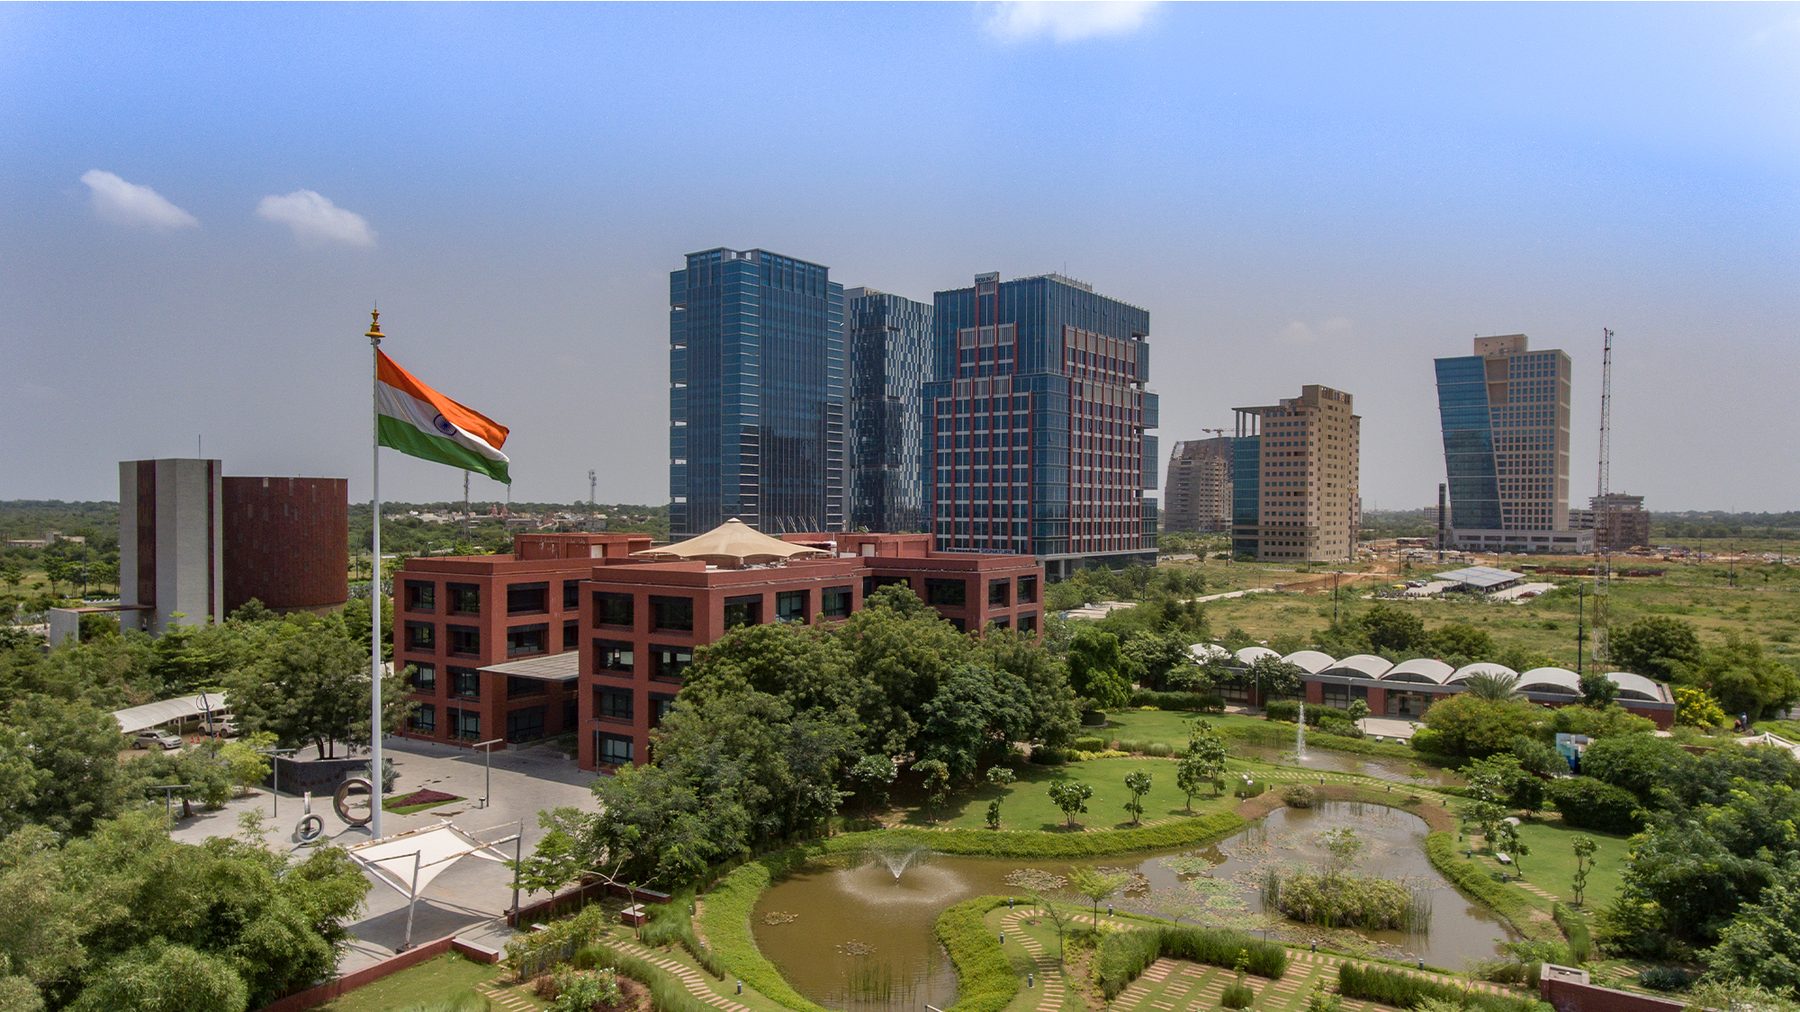
GIFT City is India’s first offshore jurisdiction, located on Indian soil.
It is a 600 acre Special Economic Zone between Ahmedabad and Gandhinagar that, for financial regulatory purposes, is legally treated as foreign territory. The functional currency inside is USD, GBP, or EUR. Not the Rupee. You never have to convert.
There is only one regulator: the International Financial Services Centres Authority (IFSCA). Not SEBI, not RBI, not IRDAI passing files between three offices in Mumbai. One regulator. One framework. One jurisdiction. Think of it as Singapore’s regulatory ease, placed in Gujarat, with direct access to Indian markets.
The simplest way to put it: GIFT City is the first time in history an NRI can invest in India’s growth without converting a single dollar into Rupees.
The Tax Math: Do NRIs Pay TDS on Mutual Fund Exits Through GIFT City?
The reason GIFT City matters is not ideology. It is arithmetic. Here are the exemptions that most NRIs do not even know exist.
How NRI Investment Income Is Taxed
Mainland India vs GIFT City IFSC | Indicative rates, vary by instrument and applicable DTAA
Income Type
Mainland India
GIFT City IFSC
Dividend income (NRI)
Up to 20%
10%
Interest on FCY deposits
Taxable
Fully Exempt
Derivative income, Sec 10(4E)
Slab / 30%
100% Exempt
Capital gains, IFSC-listed shares
20 to 30%
~9% concessional
Bonds listed before July 2023
Slab rate
4%
TDS on Mutual Fund exit
12.5 to 20%
Nil
Mainland Indian mutual funds: when you redeem, 12.5% to 20% is deducted at source. You file a return next July, claim the refund, wait 8 months. Meanwhile, your money is sitting with the Income Tax Department earning you nothing. GIFT City mutual funds: you redeem, the full amount hits your account. No deduction. No refund chase.
For an NRI redeeming ₹50 lakh, you instantly have ₹6 to ₹10 lakh more in your account versus the same fund in mainland India. The math is that direct.
How Is This Even Legal?
This is the question every careful NRI asks. GIFT City is not a loophole or grey area. It is a deliberate piece of Indian financial infrastructure built under four specific legal frameworks. Each one is written into the Income Tax Act. Each one was enacted by Parliament.
Exempts capital gains on units of specified IFSC funds for non-residents. The cornerstone provision behind the zero-TDS treatment on mutual fund redemptions.
Section 10(4E)
Derivative income exemption
Derivative income earned by non-residents through an IFSC unit is 100% exempt from Indian tax. Foundational for sophisticated trading and hedging strategies.
Section 47(viiab)
Transfer of listed securities
Exempts capital gains on transfers of specified listed securities in IFSC. Enables clean exits without a taxable event on the security itself.
Finance Bill 2025
Tax holiday extended to 2030
Explicitly extended the IFSC tax holiday to 2030, with full income-tax exemption for 10 of the first 15 years of operation.
The government built this intentionally to attract NRI capital that was previously flowing through Mauritius and Singapore. India wanted that capital onshore, but treated like offshore capital, and built an entire jurisdiction to make it happen.
This is not aggressive tax planning. This is using the structure India explicitly built for you.
Why Mauritius and Singapore Are Quietly Losing
For decades, sophisticated NRI and global capital flowed into India through Mauritius and Singapore. Then post 2017, India narrowed the Mauritius treaty. Substance requirements tightened. Singapore got more expensive. Today, running a Mauritius vehicle for India exposure requires real directors, real audits in USD, and real substance scrutiny.
GIFT City eliminates all of that. Same currency flexibility, lower setup costs, direct Indian regulation, no treaty shopping questions. And critically, from April 2026, India-focused funds can relocate from Mauritius or Singapore to GIFT City on a tax neutral basis.
The Quiet Migration of NRI & Institutional Capital
Where India-bound foreign capital is increasingly being domiciled
766+ institutions $22B+ committed USD-denominated One regulator (IFSCA)
766+ entities and $22B+ figures reflect IFSCA disclosures of registrations and aggregate commitments. Migration patterns continue to evolve through 2026.
When over 766 institutions set up shop in the same place, including JP Morgan, Barclays, Aditya Birla, DSP, ICICI Prudential, and Mirae Asset, they know something most NRIs do not.
Who Can Actually Invest Through GIFT City?
This is where most articles get vague. Let us be specific. You qualify if any of these describe you.
You can invest through GIFT City IFSC if you are
An individual holding NRI, OCI, or PIO status anywhere in the world.
A foreign national wanting India exposure without FPI registration complexity.
A family office or HNI structure abroad managing pooled capital.
An investor who wants to deploy foreign currency with no Rupee conversion, and no PIS account.
Tired of 20% TDS on every Indian mutual fund redemption, and the annual return-filing dance to claim refunds.
Until recently, most IFSC funds had a USD 150,000 minimum. That has now changed. For select IFSC retail mutual funds, the minimum has dropped to USD 500. For accredited investors, certain AIF strategies are accessible from USD 50,000. Onboarding is fully remote. No India trip, no in-person KYC, no resident account workarounds.
The barrier to entry just collapsed. And most NRIs have not noticed.
The Real Edge Is Not Tax. It Is Structural.
Tax savings are the headline. But the deeper reason serious wealth is moving here is structural. Three things change permanently when you move to a GIFT City structure.
01
One regulator. One currency. One jurisdiction.
No PIS account. No relative’s resident account. No annual ITR filings just to claim TDS refunds. No 1 to 2% conversion loss on every inflow and outflow. The operational drag simply disappears.
02
Repatriation is the default, not the exception.
When you want to take money out, it goes out the same way it came in. In dollars, without RBI approval cycles. Your money treats your global location as home, not foreign.
03
April 2026 unlocks tax-neutral fund migration.
Expect a steady migration of India-focused funds from Singapore and Mauritius into GIFT City. The capital is already moving. The question is not whether this becomes the dominant route. It is how quickly.
What This Means for Your Portfolio Right Now
If you have been investing in India as an NRI for more than three years, your structure is almost certainly out of date. That is not a criticism. The rules changed faster than the advisors did.
The right move is rarely a panic migration. It is an honest audit. Look at where your existing NRO interest is going. Look at how much TDS gets deducted on every redemption. Look at how many months you have spent waiting for refunds. Then, against that picture, consider what a parallel GIFT City structure would look like.
You do not have to liquidate your existing structure overnight. Most clients run both in parallel for the first 12 to 18 months, slowly shifting new flows and select redemptions into the GIFT City vehicle. The transition can be staged, deliberate, and stress free, if it is started in the right order.
How GVNG Approaches GIFT City for NRI Clients
This is the kind of decision where the order of operations matters more than the destination. We typically work through this with our NRI clients across four conversations.
Conversation 1, the audit. A full look at your current Indian structure. NRO interest, mutual fund redemptions, TDS history, repatriation patterns, CA fees. We quantify the silent drag in actual rupees per year.
Conversation 2, the design. We map a target GIFT City structure to your situation. The right fund category, the right minimum, the right onboarding path for your country of residence.
Conversation 3, the transition. We sequence the migration. What moves first. What stays. What gets rerouted when. Everything documented in writing, no surprises.
Conversation 4, the review. Six months in, we measure what the new structure actually saved versus the old one, in real rupees.
If your money is in India, but you are not, the structure matters more than the strategy.
One Last Thought
For 30 years, sophisticated Indian capital from abroad ran on plumbing designed for an earlier era. Mauritius. Singapore. NRO accounts and resident-account workarounds. The leakage was tolerable when there was no alternative.
Today there is an alternative. It sits on Indian soil, under Indian regulation, with offshore-style treatment, and it was built specifically for the wealth held by every NRI, OCI, and Indian-origin family abroad. If you are one of them, the most important financial conversation of your next decade is not which stock to buy. It is which jurisdiction your wealth lives in.
Questions readers ask
What is GIFT City and why does it matter for NRIs?
GIFT City is India's first International Financial Services Centre (IFSC), located in Gujarat. It lets NRIs invest in Indian funds in US dollars without converting to rupees, and offers major tax exemptions unavailable through the traditional NRO/mutual-fund route.
Do NRIs pay TDS on mutual fund exits through GIFT City?
No. Funds structured through the GIFT City IFSC allow NRIs zero TDS on mutual fund redemptions, unlike domestic mutual funds where TDS is deducted at the point of exit.
Which tax exemptions apply to GIFT City investments?
Key exemptions come under Sections 10(4D), 10(4E) and 47(viiab) of the Income Tax Act, along with the tax holiday extended in the Finance Bill 2025, which together exempt qualifying IFSC fund income and transfers from Indian tax.
How is GIFT City different from investing via Mauritius or Singapore?
GIFT City offers similar tax efficiency to offshore hubs like Mauritius and Singapore, but keeps the money onshore in India under Indian regulation (IFSCA), with a minimum investment from USD 500 and no treaty-shopping risk.
How do I invest in GIFT City as an NRI?
You need NRI, OCI or PIO status; foreign nationals and family offices abroad can invest too. You invest in foreign currency through a GIFT City IFSC fund, with no rupee conversion and no PIS account, and onboarding is fully remote. Select IFSC retail mutual funds now start at USD 500, and certain AIF strategies at USD 50,000 for accredited investors.
If Your Money Lives in India, We Should Talk
Whether you are managing a ₹50 lakh portfolio or a multi-crore family corpus from abroad, the structure beneath your investments matters more than ever. Let us audit your current setup, quantify the silent drag, and design the right GIFT City pathway for your situation.
Reviewed by Nishith Gandhi, GVNG Financial · Last reviewed: July 2026 · Sources: IFSCA, Income Tax Dept (CBDT)
Disclaimer: This content is for educational purposes only and is not investment or tax advice. Treatment varies by instrument, residency status, and applicable Double Tax Avoidance Agreement. Please consult a qualified financial or tax advisor before making any decision.
A note from the founder
Your money has come home. Its structure should too.
Many NRI families still send money to India through the same routes their parents used, and lose a part of it every year to tax and paperwork without noticing.
In shortThrough GIFT City, India's own international financial centre in Gujarat, non-residents can now hold Indian funds in US dollars, skip rupee conversion and pay zero TDS on mutual fund exits, under one regulator, IFSCA. If your money is in India but you are not, the structure matters more than the strategy.
Let us look at your family's setup together, wherever in the world you are.
GIFT City: How Smart NRI Money Is Quietly Moving Home
Summarising
The short answer
Through GIFT City, India's IFSC in Gujarat, NRIs, OCIs and PIOs can invest in India in US dollars, with no rupee conversion and zero TDS on mutual fund exits. The old NRO and mainland-fund routes leak about 2 to 3% a year, roughly ₹1 crore over 10 years on a ₹5 crore portfolio.
Minimums have dropped to USD 500 for select retail funds and the tax holiday runs to 2030. The sensible move is an audit and a staged shift, not a panic switch.
01The Cousin in Dubai. The Brother in London. The Friend in Toronto.
The cousin in Dubai, the brother in London, the friend in Toronto: most are still running the setup they made when they moved abroad, with an NRO account, SIPs, a relative's account as a routing layer and a CA who files every July.
That setup quietly costs 2 to 3% of the portfolio every year in tax friction, TDS lock-ups and currency conversion: about ₹1 crore over 10 years on a ₹5 crore portfolio, without a single bad investment. The rules changed and nobody told them.
766+ entities registered in GIFT City's IFSC, $22B+ of capital committed, a new retail minimum of USD 500, 0% TDS on mutual fund exits and a tax holiday extended to 2030.
JP Morgan, Barclays, Aditya Birla, DSP, ICICI Prudential and Mirae Asset are among those that moved in: institutional money making a structural bet, not retail enthusiasm.
03What Most NRIs Are Still Doing (And Why It Is No Longer Smart)
NRO accounts earning 6% with 30% TDS on the interest; NRE accounts that are tax-free but convert to rupees on every move; mainland mutual funds that deduct 12.5% to 20% TDS on each redemption, forcing an Indian tax return just to claim the refund.
Add a relative's resident account used to hold money, which is technically a FEMA violation, and PIS accounts as complex as running a small business. Each was right five years ago; each now drains wealth, legally and quietly.
Old way (NRO + mainland fund): 1 to 2% lost converting dollars to rupees, 30% TDS on interest, yearly CA fees and returns, 12.5 to 20% TDS on redemption, a 6 to 8 month wait for the refund, and another 1 to 2% lost converting back. Net drag: 2 to 3% a year.
New way (GIFT City fund): dollars stay dollars, interest on foreign currency deposits is exempt, one regulator, zero TDS on redemption, no Indian return for this flow, and repatriation in USD without a second conversion. Net drag: roughly zero.
On a ₹50 lakh redemption, that is the gap between getting the full amount today and waiting about 8 months to recover ₹6 to ₹10 lakh.
Gujarat International Finance Tec City is a 600 acre special economic zone between Ahmedabad and Gandhinagar that, for financial rules, is treated as foreign territory on Indian soil.
It works in USD, GBP or EUR rather than rupees, and has one regulator, IFSCA, in place of SEBI, RBI and IRDAI. Think Singapore's ease, in Gujarat, with direct access to Indian markets.
06The Tax Math: Do NRIs Pay TDS on Mutual Fund Exits Through GIFT City?
Dividends: up to 20% on the mainland against 10% in the IFSC. Interest on foreign currency deposits: taxable against fully exempt. Derivative income under Sec 10(4E): slab or 30% against 100% exempt.
Capital gains on IFSC-listed shares: 20 to 30% against about 9%. Bonds listed before July 2023: slab rate against 4%. TDS on mutual fund exits: 12.5 to 20% against nil.
Redeeming ₹50 lakh through GIFT City puts ₹6 to ₹10 lakh more in your account straight away, instead of it sitting with the tax department for months. Rates are indicative and depend on the instrument and the tax treaty.
It is not a loophole but four provisions passed by Parliament. Section 10(4D) exempts non-residents' capital gains on specified IFSC fund units (the basis of zero TDS); Section 10(4E) exempts their derivative income through an IFSC unit.
Section 47(viiab) exempts gains on transfers of specified listed securities in the IFSC, and the Finance Bill 2025 extended the IFSC tax holiday to 2030, with full exemption for 10 of the first 15 years.
India built it on purpose, to bring home the NRI capital that used to flow through Mauritius and Singapore.
Since 2017 India has narrowed the Mauritius treaty, substance rules have tightened and Singapore has become costlier. A Mauritius vehicle now needs real directors, USD audits and close scrutiny.
GIFT City gives the same currency flexibility with lower setup cost, direct Indian regulation and no treaty questions. From April 2026, India-focused funds can move from Mauritius or Singapore to GIFT City tax-neutrally.
Anyone with NRI, OCI or PIO status, foreign nationals who want India exposure without FPI registration, and family offices or HNI structures abroad, especially those tired of 20% TDS on every redemption.
The old USD 150,000 minimum has fallen to USD 500 for select retail IFSC funds, and some AIF strategies open from USD 50,000 for accredited investors. Onboarding is fully remote: no India trip, no in-person KYC.
One regulator, one currency, one jurisdiction: no PIS account, no relative's account, no tax returns just to chase refunds, no 1 to 2% conversion loss each way.
Repatriation is the default: money leaves in dollars the way it came in, without RBI approval cycles.
April 2026 opens tax-neutral fund migration, so expect India-focused funds to keep moving from Singapore and Mauritius into GIFT City.
If you have invested in India as an NRI for more than three years, your structure is almost certainly out of date.
Do not panic-migrate. Audit first (where the NRO interest goes, how much TDS each redemption loses, how long refunds take), then run both structures side by side for 12 to 18 months, moving new money and select redemptions across in stages.
Four conversations: the audit (your current structure and its yearly drag in rupees), the design (the right GIFT City fund, minimum and onboarding path for your country), the transition (what moves first and what stays, all in writing) and the review six months later, measuring what the new structure actually saved.
If your money is in India but you are not, the structure matters more than the strategy.
For 30 years, Indian money from abroad ran through Mauritius, Singapore, NRO accounts and workarounds, and the leakage was tolerated because there was no alternative.
Now there is one, on Indian soil and under Indian rules with offshore-style treatment. The biggest money question of the next decade is not which stock to buy but which jurisdiction your wealth lives in.
What GIFT City is: India's first International Financial Services Centre, in Gujarat, where NRIs invest in US dollars without converting to rupees. TDS: zero on fund redemptions through the IFSC.
The tax law: Sections 10(4D), 10(4E) and 47(viiab), plus the tax holiday in the Finance Bill 2025. Against Mauritius or Singapore: similar tax efficiency, but onshore under IFSCA.
How to invest: NRI, OCI or PIO status, a GIFT City IFSC fund in foreign currency and fully remote onboarding. Select retail funds start at USD 500.
A summary of the article above, written by GVNG Research. Every chart, table and source is in the full article. For information only, not investment advice.